
ATTIVO
Client Profile: Alice Li and Alan Smith
How tailored financial planning transformed Alice and Alan’s retirement journey.
Adapted from the original wording in Attivo Life Magazine by Joely Carey.
A shared love of science helped bring Alice Li and Alan Smith together. Years later, a shared appetite for change helped them build a business, reshape their working lives and start looking ahead to a very different kind of future.
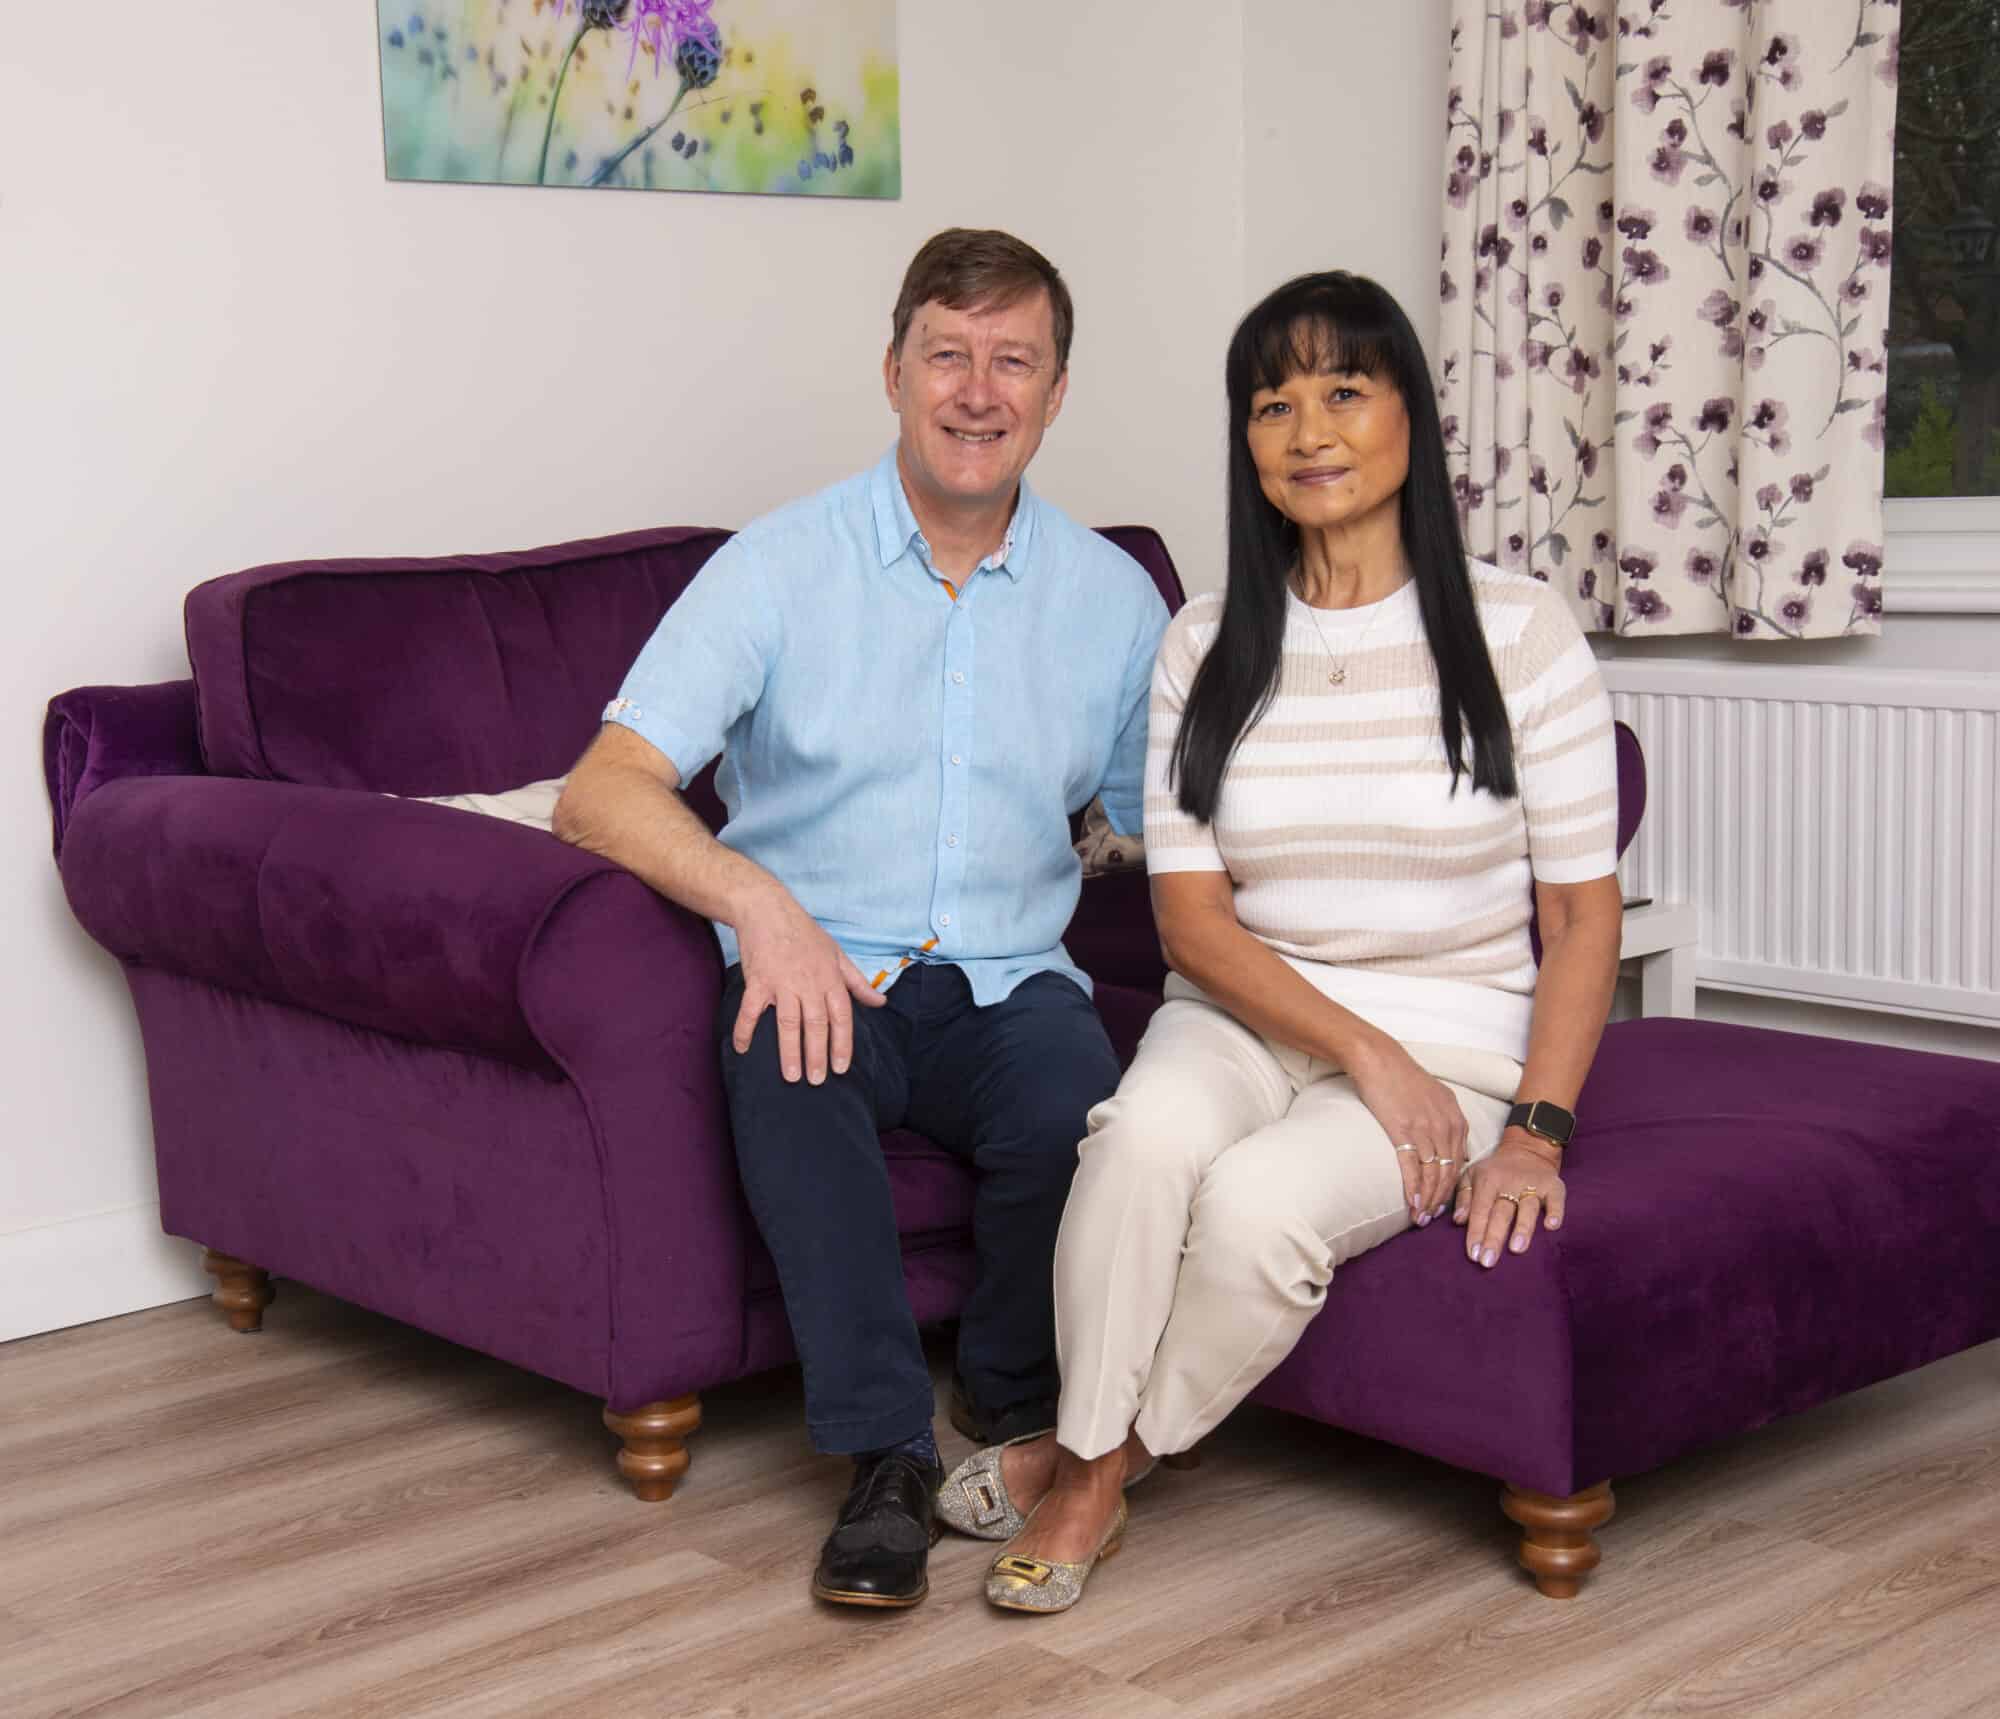
In many ways, it feels as though Alice and Alan were orbiting one another long before they finally met.
They both grew up in Bexley, South East London. They both became chartered chemists. They both began their careers at The Wellcome Foundation. Yet for years, their paths never quite crossed.
Eventually, it took a headhunting call, an unavailable colleague and a last-minute change of plans to bring them face to face.
“I came in at the last minute to show Alice around and then we ended up working for the same boss,” says Alan. Later, when they both found themselves single, their professional connection became something more.
A lifechanging decision
By the early 2000s, Alice and Alan were working in senior roles for a global pharmaceutical company in Essex. With four children between them and demanding careers, time together was precious. So, when a request to take leave at the same time was rejected, the couple made a decision that would change everything.
“I said, let’s just leave to set up a business ourselves,” says Alan. And that is exactly what they did. Both resigned, stepping away from secure senior roles to create the pharmaceutical consultancy QED-QED Ltd. “It was a risk, but a calculated one. We had talked about it previously – Alice had run a business before and together we had a specialist skill set,” says Alan.
On paper, they had every reason to back themselves. Both had led quality departments, Alan held a postgraduate qualification in Industrial Pharmaceutical Studies and was a registered Qualified Person, while Alice was a Chartered Chemist with a postgraduate qualification in management. Even so, leaving behind steady salaries was daunting.
“Doing it so quickly, we didn’t have a savings pot, we had young children, we didn’t have any clients. We left with just the shirts on our backs. Was I worried? Absolutely!” says Alice.
Are you really ready to retire?
Our pension calculator asks a few simple questions to calculate whether you may be ahead of target, on target or behind target for your planned retirement.
Their first plan was ambitious:
Build the business, work relentlessly, grow by taking on consultants and, in time, either keep it or sell it to fund retirement. Simple enough in theory; but in reality, running the business began to seep into every corner of their lives.
“We became like ships that passed in the night,” says Alan, speaking from the couple’s shared office at their family home in the Kent countryside. For Alice, the turning point was recognising what she did not want to repeat. “When my girls were younger, I hardly saw them as I was out working all the time. I didn’t want that to happen again.”
So they changed course. QED-QED would stay intentionally small, run by just the two of them, and the original five-year exit plan was put to one side. “We’re happy with our decision,” says Alan. “Yes, maybe we could have sold it by now and become multimillionaires, but we might not have made it that far.”
Keeping the business smaller did not mean thinking small.
Alice and Alan went on to work on significant pharmaceutical projects across the UK, Europe, Asia, America and Australia, including in fields such as gene therapy. Their expertise took them around the world and allowed them to build a successful business in a way that still reflected their values.
In the early days, however, the focus was firmly on making the business work. “We didn’t really think about pension planning,” says Alice.
Alice and Alan’s plans began to change when they switched Financial Adviser and stepped up again when they joined Attivo.
“Attivo helped us understand how to plan for retirement and they made sure they understood how we wanted to live when we reached that stage,” says Alice.
That next stage is now coming into view. Alan describes himself as semi-retired: “I’ll keep on until I don’t enjoy it anymore.” Alice agrees that retirement is something to ease into rather than step into overnight. “You must work up to it, change your habits. We want to realign our lives to get more enjoyment out of the next phase.”
Considering phased retirement?
Discover its benefits, drawbacks, and how you can start thinking about planning for it in our expert article:
They have already begun that realignment.
Gardening, Latin and ballroom dancing have joined the weekly routine, while travel plans are gathering pace. This year alone, their itinerary includes Hong Kong, Singapore, a family wedding, a Kenyan safari, Zanzibar, San Francisco and Hawaii.
“Attivo has helped us realise that we have done enough to be able to enjoy this early phase of retirement, and that’s been really comforting,” says Alan. Alice nods. “They’re not just a wealth management company; they’re not just about the mathematics; they ask what we want from our life and then set about helping us achieve that. They’ve been great.”
Thinking about how to prepare for your next phase of life? We’re here to help.
Together, we’ll explore your current circumstances and the lifestyle and goals that you want to achieve, before building a financial plan to help you throughout your journey.
It all starts with arranging your free, no-obligation consultation with us.
Important information
We offer a free initial consultation to discuss your goals and next steps. If you decide to go ahead with advice, charges may apply – these will be explained before you commit.
This is one client’s experience; customer testimonials are illustrative, it may not be representative as outcomes depend on individual circumstances. Pension and investment values can go down as well as up, and you may get back less than you originally invested. A pension is a long-term investment, and your eventual income may depend on factors including fund performance, charges and tax legislation. Retirement income options such as drawdown can offer flexibility, but income is not guaranteed and will depend on investment performance, charges and how much you withdraw. Pension consolidation is not right for everyone and may result in the loss of valuable benefits or guarantees. Taking income through drawdown reduces the value of your pension fund and could affect the level of income available in the future.