
ATTIVO
There Are No Stupid Questions: Inflation
Ryan Wright
At Attivo, we answer any questions you may have about lifestyle financial planning. Ryan Wright, one of our Associate Directors, talks about inflation.
Ryan Wright says: “In the role of lifestyle financial planner, you get to know what’s important to your clients, what really matters. Over a period of time, which sometimes spans decades, you reach a position where you’re more of a professional friend than an adviser. I love my job and I feel I’m in a privileged position, I hear about people’s hopes and dreams and want to support them as best as I can to achieve them.”
Q How does inflation affect my investments?
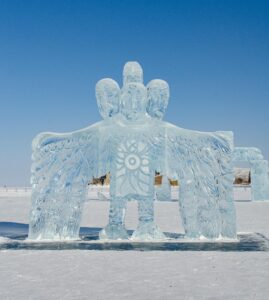
A Essentially, inflation impacts the buying power of your money over time. For people who keep their money in cash (in say, their bank account), this is usually for comfort reasons but it’s a wasted opportunity and will lose you money because of the paltry rates of interest they usually pay. Think of it like this: a loaf of bread costs you £1 today and next year, after inflationary pressure it could be £1.10 but perhaps your bank-held investments have only gone up to £1.05. Yes, you’ve made money, but in real terms, your buying power has gone down. When you compound this over a long period of time it becomes a bigger issue and if you’re holding that money in ‘cash’, then you’ll fall further and further behind. I describe it as being similar to the ice sculpture at a wedding – at the beginning, the ice sculpture looks stunning and everyone’s delighted by it but by the end of the night it’s gone. You don’t really see it melting away, it happens without anyone noticing and cash, frankly, is the same.
Q Inflation is putting a squeeze on our income and we’re worried about our investments, what should we be doing?
A Over the past six months, clearly, inflation has been causing worry amongst our clients. Every market fall is different, but in some ways they’re all the same – it’s a temporary decline that is best dealt with by doing nothing to give it the best chance to recover. One of the weirdest phenomena of our industry is that when markets collapse, people want to withdraw their investments. We are hard-wired as humans not to want to lose anything and so it takes mettle to hold your nerve as the market is going down. It plays into the fear of running out of money. Whilst past performance cannot be relied on as a guide to future returns, history tells us that markets will and do generally recover. As long as you have enough emergency cash on deposit to call upon in times of stress, my advice is usually to sit tight and hang in there even if it feels unnatural. “In the role of lifestyle financial planner, you get to know what’s important to your clients, what really matters. Over a period of time, which sometimes spans decades, you reach a position where you’re more of a professional friend than an adviser. I love my job and I feel I’m in a privileged position, I hear about people’s hopes and dreams and want to support them as best as I can to achieve them.” At Attivo, we answer any questions you may have about lifestyle financial planning.
“The effect of inflation is like an ice sculplture at a wedding… you don’t see it melting away, but by the end of the night it’s gone.”
Q What can I do to protect my money from the effects of inflation?
A You need to make sure that your investment portfolio is going up by at least the amount the cost of living is rising, although you should always remember that capital is at risk and investment returns aren’t guaranteed. You can’t rely on cash with interest rates so low and it’s best not to invest in a portfolio made up entirely of government bonds and corporate bonds. They yield low returns over the long run (unless you’re taking big risks on bonds with a high chance of default). You can’t rely on gold and you don’t want to put your eggs in the Bitcoin basket. Invest in the best businesses in the world that will continue to thrive – that’s what we do for our clients. History shows us that if the money is invested for long enough it will usually perform well. As the saying goes: it’s time in the market not timing the market. It’s also a good idea to make sure your portfolio is as tax efficient as possible because tax is a drag on returns. Mitigate this by looking at each of the wrappers and their different features – there are ways to reduce or even eliminate tax with the right products.
Jargon Buster: ‘Wrapper’
A ‘tax wrapper’ or simply ‘wrapper’ is a little like a box, used to hold your money. It means your money is in an account which gives you some protection from tax. You might have one wrapper for an ISA, another for pensions and so on.
Different wrappers do different jobs, just as different size or shape boxes do. It’s always essential to seek advice on which is the most suitable ‘box’ for your circumstances.
Prepare for your next phase of life
The value of investments may fall as well as rise. If you have any questions, please email our Client Services team on clientservices@attivo.co.uk or call us on 01242 585444.