
ATTIVO
Ask us anything: Starting pensions early
Sebastian Field is an Associate Financial Planner at Attivo and one of our network of planners in the UK.
Sebastian says: ‘It’s a sensible idea to start a pension young because it offers extra security and wealth to rely on in retirement. If you know you have a source of wealth saved up for later in life, it could also free up money earlier, for example for a house deposit.’
Starting a pension for yourself
Q Why is it a good idea to start a pension young and what are the benefits?
A Not only does a pension provide extra security and peace of mind that you have a source of income to rely on in retirement, if you started saving towards your pension when you were young and already have a lot of money saved, it could have the indirect benefit of giving you more flexibility when it comes to big purchases such as a house or a car. You can’t take money out of your pension savings but with a headstart on your retirement planning you may be able to divert savings to other priorities without sacrificing your longer-term goals.
Q My daughter has started working as a freelancer straight from university and isn’t putting anything into her pension. What would you advise?
A Freelancers don’t benefit from auto-enrolment (where the employer enrols you in its workplace pension scheme and contributes to it alongside your own contributions), but if they are self-employed, they can still set up a SIPP (Self-Invested Personal Pension). They can contribute as much as they can afford (subject to limits) while balancing other needs, like saving for a house or clearing university debt. My advice is that saving anything is better than nothing and investing in a pension means that you will benefit from tax relief.
As an example, if you’re a basic rate taxpayer you pay £20 for every £100 of income. Put the remaining £80 into a pension pot and your daughter would be able to claim back £20 on her tax return. Tax relief gives her back that £20, so it’s a win-win! But while it’s important to start your pension early, you have to balance that with affordability. You can be flexible with what you contribute and how often, and if you find you earn more one month, then you can put a bit more in the ‘pot’.
Q My 20-something grandchildren are keener on partying than putting their money in a pension. How can I make it clear to them what this means for their retirement when they think pensions are boring?
A It’s understandable that young people find it hard to relate to pensions. I suspect they hear the word ‘pension’ and think: ‘That’s boring and for old people, what’s that got to do with me?’
People often don’t understand the benefits, and the word can be off-putting. I would like to rename ‘pension’ to something like ‘tax efficient long-term investment plan’. I actually find pensions really exciting – they are so flexible and brilliant for wealth growth. My advice would be to talk to your grandchildren and explore their understanding of pensions, point out the benefits, and remind them that the current state pension is just £10,600 a year (provided you have paid the full 35 years of National Insurance contributions). That’s not a lot to live on, and that’s why it’s so important to create that extra provision now.
Here at Attivo, our lifestyle Financial Planners guide our clients through the options and find the right plan for them, and we often do this with our client’s children or grandchildren, too. We can talk to them together and explain the best ways to save and invest so they have a comfortable retirement.
Investments to help family members with their pensions
Q Pension changes are happening all the time. How can we ensure our children or grandchildren are best prepared for the future?
A A good thing you can do to help y our children or grandchildren is to put money aside in a Junior SIPP (Self-Invested Personal Pension). It’s like a trust fund where your money is locked away for your child or grandchild’s future. It currently benefits from 20 per cent tax relief, which means that for every 80p you pay into a Junior SIPP this is automatically topped up to a £1. The maximum contribution you can make each year is £2,880 with 20 per cent tax relief automatically applied taking it up to £3,600. The money in the SIPP can be invested, and the minimum contributions can be very low.
Q Are pensions the only way we can help prepare our children for their future?
No, it’s not the only way. You could save for the future by setting up a Junior ISA with a £9,000 limit a year. Bear in mind, however, that ownership transfers to the child when they reach 18, so they will have full access to the money and could spend it all if they wanted.
I’ve seen clients use Junior ISAs to save for university for their child or to help their children to pay for a house when they are older.
Q How does the Junior SIPP work and how do I go about setting one up?
A Anyone can contribute to a Junior SIPP, but it has to be set up by a parent or guardian. The money is locked away until the ‘child’ is 55 (rising to 57 in 2028), and the account management is handed over to the child when they turn 18 (but they still can’t access the money until they are 55). It’s a tax-efficient way to save and contributions can be from £20 a month depending on the individual provider.
Jargon Buster: Junior SIPP
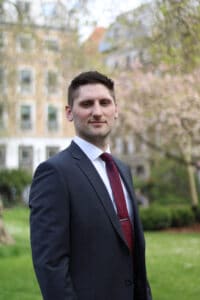
‘A Junior SIPP is a type of personal pension that is managed on behalf of a child by a parent or legal guardian until the child turns 18,” says Sebastian Field, pictured.
‘It works in a similar way to a standard Self Invested Personal Pension (SIPP), giving investors the flexibility to manage how and where their money is invested.’
Disclaimer: The value of investments may fall as well as rise. If you have any questions, please email our Client Services team on clientservices@attivo.co.uk or call us on 01242 585444.
Prepare for your next phase of life
If you’d like to bring your vision for the future to life, why not talk to Attivo about our unique Lifestyle Financial Planning and how we can help with the next stage. Click here to contact us.